Most advisors manage portfolios. We architect the entire balance sheet of your life — income, investments, tax, insurance and estate — so every dollar is placed with intent. If you own a company, that goes into the model too.
Your income is the engine. How it's structured is the transmission. Most people redline the engine and never touch the gears — then hand a third of the output to the CRA. We exist to close that gap: integrating tax, investment, insurance and estate strategy into one deliberate architecture.
We work with professionals, families and business owners — because the planning problems you face are structural, not generic.
Every recommendation is modelled after-tax and after-fee, across every account you hold. If it doesn't survive that math, it doesn't reach your desk.
Each service stands alone. The value compounds when they're designed together.
One integrated plan for growing, protecting and transferring wealth — modelled after-tax at every step, and built around your corporation if you have one.
Disciplined portfolio construction across registered, personal and corporate accounts — asset allocation, risk, and after-fee returns you can actually measure.
A protection architecture for your family — and your company, if there is one. Life, disability, critical illness and liability, designed as one system.
Wills, trusts and beneficiary design that keep your estate intact — and keep the same dollar from being taxed twice.
For those who own a company: corporate structure, key-person coverage, funded buy-sell agreements and succession — the planning layer most operating companies are missing.
Give more to the causes you choose and less to tax — gifts in kind, donation timing, and legacy structures that multiply impact.
Home financing that fits the whole plan — renewals, refinancing and debt structured with an eye on rate and deductibility.
Financing for owner-occupied and investment property — structured through the right entity, on terms that serve the balance sheet.
Term to permanent, personal to corporate-owned — coverage sized to real obligations and positioned as an asset, not an expense.
Emergency medical and trip protection for you, your family and your snowbird months — wherever the itinerary goes.
Your income is the engine of every plan. Own-occupation coverage — plus business overhead protection if you are self-employed — keeps it running when you can't.
RRSP or TFSA. Pay down the mortgage or invest. Salary or dividends. Most of these decisions turn on arithmetic — so we built the arithmetic and put it somewhere you can use it without booking a meeting first.
Open the CalculatorsFour stages. No product pitch before stage three — ever.
Two meetings. We map what you own, what you owe, how you're taxed — and what you actually want the money to do.
A written plan modelling every recommendation after-tax — with the do-nothing case set beside it, so you can see what each decision is worth.
Brent quarterbacks your accountant, lawyer and anyone else already advising you, so the plan is implemented once, correctly, in the right order.
Tax law moves. Your life moves. Every year we re-run the model and adjust the plan before the deadline, not after it.
No hand-offs to juniors. The advisor you meet is the advisor who runs your plan.
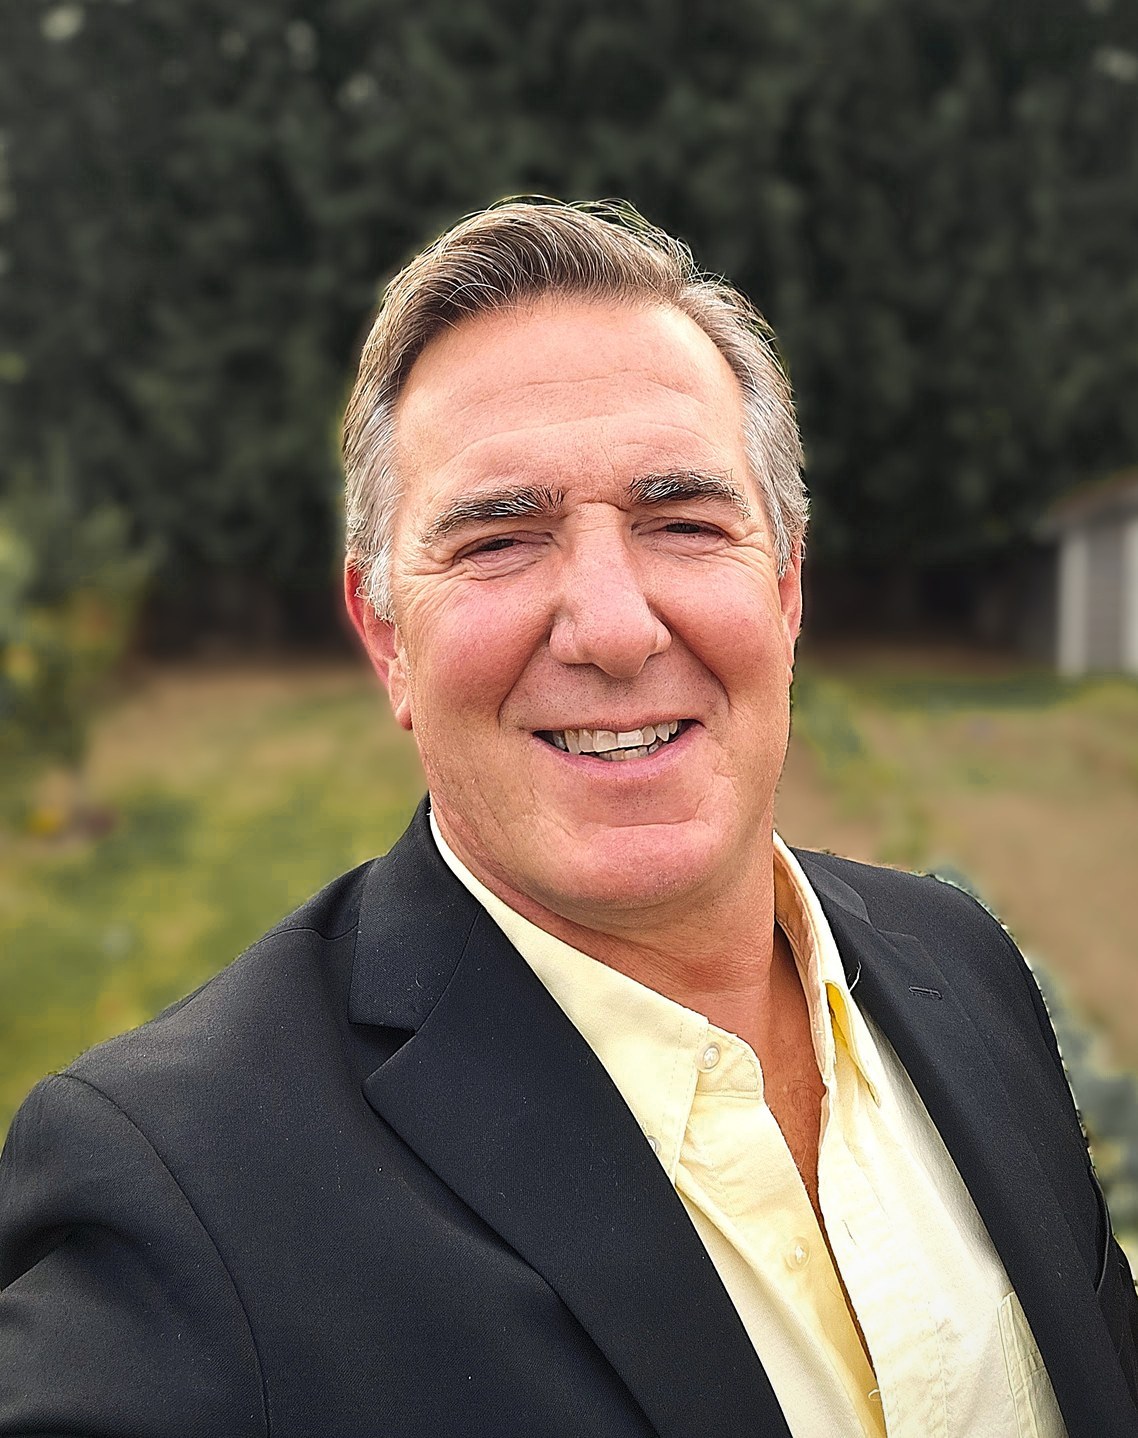
Brent grew up in the interior of British Columbia and studied at the University of Victoria. Before he advised anyone else on their money, he ran businesses of his own — several of them, successfully — so payroll, margin and the weight of a bad quarter have never been abstractions to him.
He spent years as a private debt broker before deciding the work was the wrong shape. Debt is transactional: the deal closes and the relationship ends with it. Wealth management rewards the opposite instinct — advice given carefully at forty-five is still compounding at seventy — and he wanted to be there to find out whether he had been right.
Family is why most of his clients are doing any of this, and it is why he is too. The rest is uncomplicated: he likes the work, he is in no rush to move anyone through it, and the best hour of most weeks is still a first conversation with someone he has not met.
A 45-minute diagnostic conversation. No cost, no deck, no product. If we can't add value, we'll tell you in the first meeting.
Book the DiagnosticTell us a little about you. We'll reach out within one to two business days to schedule your 45-minute diagnostic.